Neha lived in Pune. She spent about ₹40000 a month on groceries and food delivery and online shopping. Her first card gave one point per ₹100 and nothing else. A friend earned 5 percent cashback on the same spends. She searched for the Best Credit Cards in India 2026. Every list ranked a different card first.
She then built one table. She listed each card’s fee and headline cashback and monthly cap. She matched the card to her own spending. This guide follows her method for the Best Credit Cards in India 2026.
Best Credit Cards in India 2026: Quick Answer
Cashback SBI Card gives 5 percent on online spends for a ₹999 fee. Amazon Pay ICICI gives 5 percent on Amazon for Prime members with no fee. HSBC Live+ gives 10 percent on dining and groceries up to ₹1200 a month. HSBC TravelOne gives about 4 percent on travel spends.
Scapia gives 20 percent coins on travel bookings with zero forex markup and no fee. The Best Credit Cards in India 2026 match your biggest spending category. Pay the full bill every month or the rewards vanish into interest. That rule sits above every list of Best Credit Cards in India 2026.
How We Built the List
We used a card comparison updated on 7 October 2026. It lists fees and reward rates and caps for 20 cards. We grouped them into cashback and lifetime free and travel. We added cost rules such as interest and forex markup from issuer schedules.
Reward rates and caps change without notice. Offers such as a free first year expire. Treat this as a map of the Best Credit Cards in India 2026. Confirm the current terms on the issuer site before you apply.
Cashback Cards Compared
Cashback cards pay a share of spending back as statement credit. The best rates sit in one or two categories with a monthly cap. The table shows five strong cashback cards.
Best Credit Cards in India 2026: Cashback Cards (CardInsider 7 October 2026)
| Card | Fee (plus GST) | Headline cashback | Fee waiver |
|---|---|---|---|
| Cashback SBI Card | ₹999 joining and yearly | 5% on online spends and 1% offline; cap ₹4000 per cycle | Not stated |
| HSBC Live+ | ₹999 joining and yearly | 10% on dining and groceries and shopping and utilities (cap ₹1200 a month); 1.5% elsewhere | On ₹2 lakh yearly spend |
| Flipkart Axis Bank | First year free (limited offer); ₹500 yearly | 5% on Flipkart and Cleartrip; 7.5% on Myntra; 1% elsewhere | On ₹3.5 lakh yearly spend |
| Swiggy Ornge HDFC | ₹500 joining and yearly | 5% on Swiggy app; 1% on other eligible spends | On ₹1.5 lakh yearly spend |
| Amazon Pay ICICI | Lifetime free | 5% on Amazon for Prime; 3% non-Prime; 2% partners; 1% elsewhere | Not needed |
Cashback SBI Card suits broad online spending. HSBC Live+ suits households that spend on groceries and dining. Amazon Pay ICICI costs nothing. Together they lead the cashback side of the Best Credit Cards in India 2026.
Lifetime Free Cards
A lifetime free card has no joining fee and no yearly fee. Rewards are lower than paid cards but the cost is zero. These cards suit first time users and low spenders. Scapia stands out with zero forex markup.
Best Credit Cards in India 2026: Lifetime Free Cards
| Lifetime free card | Headline reward | Best use |
|---|---|---|
| Amazon Pay ICICI | 5% on Amazon for Prime members | Amazon shoppers |
| IDFC FIRST Wealth | 10X reward points per ₹200 on dining and travel and international spends | High spenders who qualify |
| IndusInd Bank Tiger | Up to 6 accelerated points per ₹100 | Everyday spends |
| Scapia | 20% Scapia Coins on travel bookings; 10% elsewhere | Frequent travellers who want zero forex markup |
| Axis Bank Privilege (Visa variant) | 10 EDGE points per ₹200 (about 1%) | Simple no fee card |
IDFC FIRST Wealth needs a higher income to qualify. IndusInd Tiger and Axis Privilege are simple starters. Amazon Pay ICICI is the strongest free card for shoppers. They form the free tier of the Best Credit Cards in India 2026.
Travel and Premium Cards
Travel cards pay more on flights and hotels and foreign spends. They add lounge access and lower forex markup. Fees run ₹2500 to ₹5000 a year. They pay off only for frequent travellers. The Best Credit Cards in India 2026 for travel need the fee maths first.
Best Credit Cards in India 2026: Travel and Premium Cards
| Travel or premium card | Fee (plus GST) | Headline reward | Fee waiver |
|---|---|---|---|
| HSBC TravelOne | ₹4999 joining and yearly | 4 points per ₹100 on flights and travel platforms and international spends (about 4%) | Not stated |
| HDFC Regalia Gold | ₹2500 joining and yearly | 5 points per ₹200 on eligible retail spends plus lounge access | Not stated |
| Equitas PowerMiles | ₹5000 joining and yearly | 3 points per ₹100; 3X on international and online | On ₹4.8 lakh spend in an anniversary year |
| Scapia | Lifetime free | 20% coins on travel bookings and no forex markup | Not needed |
HSBC TravelOne gives about 4 percent on travel. Scapia gives zero markup abroad with no fee. HDFC Regalia Gold adds lounge access for ₹2500. Frequent flyers pick from this tier of the Best Credit Cards in India 2026.
The Hidden Costs That Erase Rewards
Interest on unpaid balances runs about 3 to 3.75 percent a month. That is 36 to 45 percent a year. One month of carried balance wipes out a year of cashback. Late fees and forex markup and cash withdrawal fees add to the damage.
Best Credit Cards in India 2026: Hidden Costs to Avoid
| Cost item | Typical figure | How to avoid it |
|---|---|---|
| Interest on unpaid balance | About 3% to 3.75% a month (36% to 45% a year) | Pay the full statement every month |
| Late payment fee | ₹500 to ₹1300 by slab | Set autopay for the full amount |
| Foreign currency markup | About 2% to 3.5% plus GST | Use a zero markup card abroad |
| Cash withdrawal | 2.5% fee plus interest from day one | Never withdraw cash on a card |
| Fuel surcharge | 1% (often waived up to a cap) | Check the waiver cap |
Pay the full statement every month by autopay. Use a zero markup card abroad. Never withdraw cash on a card. Those three rules protect the value of the Best Credit Cards in India 2026.
Top 5 Picks by Spending Pattern
The Best Credit Cards in India 2026 depend on where your money goes. These five patterns cover most users. Each maps to a card from the tables above.
Best Credit Cards in India 2026: Top 5 Picks by Spending Pattern
| Spending pattern | Pick | Why |
|---|---|---|
| Mostly online shopping | Cashback SBI Card | 5% online with ₹4000 monthly cap |
| Amazon heavy and no fee | Amazon Pay ICICI | 5% for Prime members and lifetime free |
| Dining and groceries and bills | HSBC Live+ | 10% on those categories up to ₹1200 a month |
| Flights and foreign travel | HSBC TravelOne or Scapia | About 4% on travel or zero forex markup |
| First card with no fee | Axis Bank Privilege or IndusInd Tiger | Simple rewards with no yearly cost |
1. Mostly Online Shopping: Cashback SBI Card
The card pays 5 percent on online spends and 1 percent offline. Cashback is capped at ₹4000 per cycle. The fee is ₹999 plus GST. A ₹40000 monthly online spend earns ₹2000 a month.
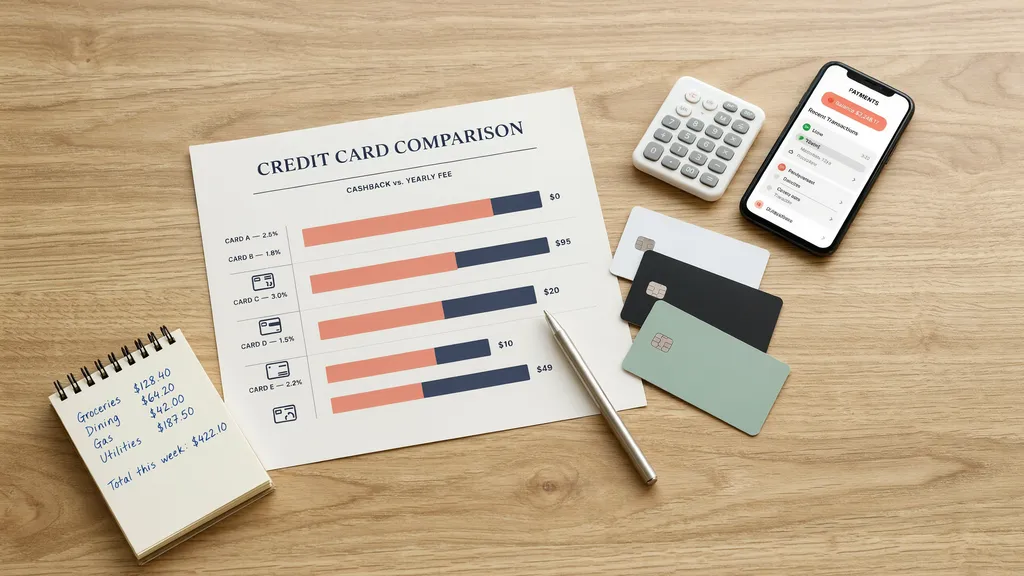
That is ₹24000 a year against a ₹999 fee. This is the online pick in the Best Credit Cards in India 2026.
2. Amazon Heavy and No Fee: Amazon Pay ICICI
The card is lifetime free. Prime members earn 5 percent on Amazon. Non-Prime members earn 3 percent. Partner merchants pay 2 percent and other spends pay 1 percent. Cashback lands as Amazon Pay balance.
Heavy Amazon shoppers get the best free return here. This is the no fee pick in the Best Credit Cards in India 2026.
3. Dining and Groceries and Bills: HSBC Live+
The card pays 10 percent on dining and groceries and shopping and utility bills. The cap is ₹1200 a month. Other spends earn 1.5 percent. The fee is ₹999 and is waived on ₹2 lakh yearly spend.
A ₹12000 monthly grocery and dining spend hits the cap. This is the household pick in the Best Credit Cards in India 2026.
4. Flights and Foreign Travel: HSBC TravelOne or Scapia
HSBC TravelOne pays 4 points per ₹100 on flights and travel platforms and international spends. That is about 4 percent. The fee is ₹4999. Scapia is free and pays 20 percent coins on travel bookings with zero forex markup.
Pick TravelOne for high spend and Scapia for zero cost. These are the travel picks in the Best Credit Cards in India 2026.
5. First Card With No Fee: Axis Bank Privilege or IndusInd Tiger
Axis Bank Privilege Visa variant is lifetime free with 10 EDGE points per ₹200. IndusInd Tiger is free with up to 6 points per ₹100. Both build a credit history without a fee. Rewards are modest.
Upgrade after a year of full payments. These are the starter picks in the Best Credit Cards in India 2026.
How to Qualify
Issuers check income and credit score and existing debt. Most entry cards need a monthly income of ₹25000 to ₹30000. Premium cards need far more. A credit score above 750 gets the best approval odds. Salaried applicants find approval easier than new freelancers.
Apply for one card at a time. Each application creates a hard enquiry. Keep utilisation below 30 percent of the limit. Those habits open the door to the Best Credit Cards in India 2026.
For wider context see the World Economic Forum section on financial and monetary systems. The OECD finance page offers comparative data on consumer credit. Both add background to the Best Credit Cards in India 2026.
5 Costly Mistakes Cardholders Make
Mistake 1: Paying Only the Minimum
Interest of 36 to 45 percent a year destroys rewards. Pay the full statement. That is rule one for the Best Credit Cards in India 2026.
Mistake 2: Ignoring the Cap
A 10 percent rate with a ₹1200 cap is ₹12000 of spend. Spend beyond the cap on another card.
Mistake 3: Paying Fees You Cannot Recover
A ₹5000 card needs ₹5000 of extra value. Count lounge visits and points at real value. Downgrade if it falls short.
Mistake 4: Using Cards Abroad Without Checking Markup
A 3.5 percent markup on ₹2 lakh of holiday spend is ₹7000. Carry a zero markup card.
Mistake 5: Holding Too Many Cards
Five cards mean five bills and five caps to track. Two or three well chosen cards beat five. Keep the Best Credit Cards in India 2026 to a short list.
Action Plan: Choosing the Best Credit Cards in India 2026
Step 1: Map Three Months of Spending
List spends by category from bank statements. Find the two biggest categories.
Step 2: Match the Category to a Card
Pick the card with the highest rate in your top category. Check the monthly cap against your spend.
Step 3: Do the Fee Maths
Multiply yearly spend by the rate. Subtract the fee. Keep the card only if the number is clearly positive.
Step 4: Check Eligibility
Confirm income and score requirements. Apply for one card. Wait for the result before the next.
Step 5: Set Autopay and Review Yearly
Set autopay for the full statement. Review rates and fees each year. That completes your Best Credit Cards in India 2026 plan.
Also read: Best Personal Loan Interest Rates in India 2026: Bank-wise EMI
Frequently Asked Questions
Q1: Which is the best cashback credit card in India?
Cashback SBI Card leads for broad online spending. It pays 5 percent online and 1 percent offline. The cap is ₹4000 per cycle and the fee is ₹999 plus GST. HSBC Live+ pays 10 percent on dining and groceries and shopping and utilities. The cap is ₹1200 a month. Amazon Pay ICICI pays 5 percent on Amazon for Prime members with no fee. Flipkart Axis pays 5 percent on Flipkart and 7.5 percent on Myntra. The Best Credit Cards in India 2026 for cashback depend on where you spend. Pick the card whose top category matches yours. Check the cap. Pay in full every month to keep the cashback.
Q2: Which lifetime free credit card is best?
Amazon Pay ICICI is the strongest free card for shoppers. Prime members earn 5 percent on Amazon. Scapia is free and pays 20 percent coins on travel bookings with zero forex markup. IDFC FIRST Wealth is free and pays 10X points on dining and travel. It needs a higher income. IndusInd Tiger and Axis Bank Privilege Visa are simple free starters. The free Best Credit Cards in India 2026 suit first time users and low spenders. Rewards are lower than paid cards. The cost is zero so any reward is a gain. Build a payment history for a year. Then consider a paid card if the maths works.
Q3: Is a ₹5000 travel card worth it?
Only for frequent travellers. HSBC TravelOne charges ₹4999. It pays about 4 percent on flights and travel platforms and international spends. A traveller spending ₹3 lakh a year on those categories earns about ₹12000 in points. That beats the fee. A traveller spending ₹50000 earns ₹2000 and loses money. Add lounge visits at their real value. Scapia gives zero forex markup with no fee at all. The Best Credit Cards in India 2026 for travel must clear the fee first. Do the sum with your own spend. Downgrade or cancel if the number turns negative. Check whether a spend based waiver exists.
Q4: How much interest do credit cards charge in India?
Most cards charge about 3 to 3.75 percent a month on unpaid balances. That is 36 to 45 percent a year. Interest starts from the transaction date once you carry a balance. Cash withdrawals attract a 2.5 percent fee plus interest from day one. Late payment fees run ₹500 to ₹1300 by slab. One month of carried balance can erase a year of cashback. The Best Credit Cards in India 2026 pay off only when the statement is cleared. Set autopay for the full amount. Keep a buffer in the bank account. Treat the card as a payment tool and not a loan. Use a personal loan if you need to borrow.
Q5: What credit score do I need?
A score above 750 gives the best approval odds for most cards. Entry cards sometimes approve scores in the 700s. Premium cards want higher scores and higher income. Most entry cards need a monthly income of ₹25000 to ₹30000. Salaried applicants find approval easier. Each application creates a hard enquiry so apply for one card at a time. Keep utilisation below 30 percent of your limit. Pay every bill on time. The Best Credit Cards in India 2026 reward a clean history. Check your score free on a bureau site before you apply. Fix errors first. A secured card against a fixed deposit helps new users build a score.
Q6: How many credit cards should I hold?
Two or three is enough for most people. One cashback card for your biggest category. One travel or zero markup card if you travel. One free backup card. More cards mean more bills and more caps to track. Missed payments hurt your score. The Best Credit Cards in India 2026 work best as a small set. Spread spending to use each cap fully. Close cards you no longer use after checking the effect on your score. Keep the oldest card open for history. Review the set once a year. Cancel a paid card if the fee no longer clears. Keep total limits sensible.
Q7: Do reward points expire?
Often yes. Many issuers expire points after two or three years. Some cards such as cashback cards credit the statement directly so nothing expires. Travel points can expire or lose value when the issuer changes the redemption rate. Read the expiry rule before you pick a card. Redeem points every few months rather than hoarding. The Best Credit Cards in India 2026 for simple users pay cashback to the statement. Points cards suit people who redeem for flights at good rates. Check the transfer partners and the conversion ratio. Watch for devaluation notices by email. Set a reminder to redeem. Unused points are lost value.
Q8: Which card is best for foreign travel?
Scapia stands out with zero forex markup and no fee. It pays 20 percent coins on travel bookings. HSBC TravelOne pays about 4 percent on international spends. It charges a markup and a ₹4999 fee. Most other cards charge about 2 to 3.5 percent markup plus GST on foreign spends. On ₹2 lakh of holiday spend that is up to ₹7000. The Best Credit Cards in India 2026 for travel abroad are zero markup cards. Carry one zero markup card and one backup. Pay in local currency at the terminal. Decline dynamic currency conversion. Inform the issuer of travel dates. Keep the helpline number saved.
Q9: Should I pay the annual fee or ask for a waiver?
Check the spend based waiver first. HSBC Live+ waives the fee on ₹2 lakh yearly spend. Flipkart Axis waives it on ₹3.5 lakh. Swiggy Ornge HDFC waives it on ₹1.5 lakh. Equitas PowerMiles waives it on ₹4.8 lakh. If your spend falls short call the issuer and ask for a waiver. Issuers often agree for good customers. If they refuse compare the fee with the rewards earned. The Best Credit Cards in India 2026 should earn more than they cost. Downgrade to a free variant if the fee cannot be recovered. Never pay a fee out of habit. Review this every renewal.
Q10: Can a student or new earner get a credit card?
Yes with limits. Students can get secured cards against a fixed deposit. New earners with a monthly income of ₹25000 or more can apply for entry cards. Lifetime free cards such as IndusInd Tiger and Axis Bank Privilege suit a first application. Amazon Pay ICICI also approves many new earners. Build a payment history for a year. The Best Credit Cards in India 2026 for beginners carry no fee. Keep the limit low and pay in full. Avoid cash withdrawals. Apply for a cashback card after the first year. A clean first year opens doors to better cards. Never apply for several cards at once.
Conclusion
The Best Credit Cards in India 2026 match your biggest spending category. Cashback SBI Card and HSBC Live+ lead on cashback. Amazon Pay ICICI and Scapia lead on no fee value. HSBC TravelOne leads on travel rewards. Interest of 36 to 45 percent a year erases every reward on a carried balance.
Map three months of spending. Match the top category to a card. Do the fee maths. Set autopay for the full amount. That is how to choose the Best Credit Cards in India 2026.
This guide on the Best Credit Cards in India 2026 is general information. It is not financial advice. Fees and rates and caps change. Confirm all terms on the issuer’s site before you apply.