Vikram lived in Chandigarh. He was 31 with a home loan and a two year old daughter. His employer gave a small group life cover. It would end the day he changed jobs. He searched for the Best Term Insurance Plans in India 2026. Every site showed a different premium for the same ₹1 crore.
He then built one table. He listed each plan’s claim settlement ratio and premium and riders. He fixed his cover need first and then compared plans. This guide follows his method for the Best Term Insurance Plans in India 2026.
Best Term Insurance Plans in India 2026: Quick Answer
Five plans lead most 2026 lists. HDFC Life Click 2 Protect Supreme Plus has a 99.6 percent claim settlement ratio. Tata AIA Sampoorna Raksha Promise and Axis Max Life Smart Term Plan Plus follow. Bajaj Life eTouch II and ICICI Pru iProtect Smart Plus complete the five.
A non-smoking man aged 30 pays about ₹8856 to ₹10440 a year. That is for ₹1 crore cover to age 60 per one October 2026 comparison. Pick the plan with a high claim ratio and the riders you need. That is the core of the Best Term Insurance Plans in India 2026.
How We Built the List
We used a term plan comparison updated on 20 October 2026. It draws claim ratios from IRDAI data as a three year weighted average. Premiums come from its May 2026 data. The profile is a 30 year old non-smoking graduate earning ₹10 lakh. We added premium rules from a March 2026 industry article.
Premiums depend on age and smoking and health and city. Treat the figures as a starting point. Use this guide as a map of the Best Term Insurance Plans in India 2026. Get a real quote from two insurers.
Five Plans Compared
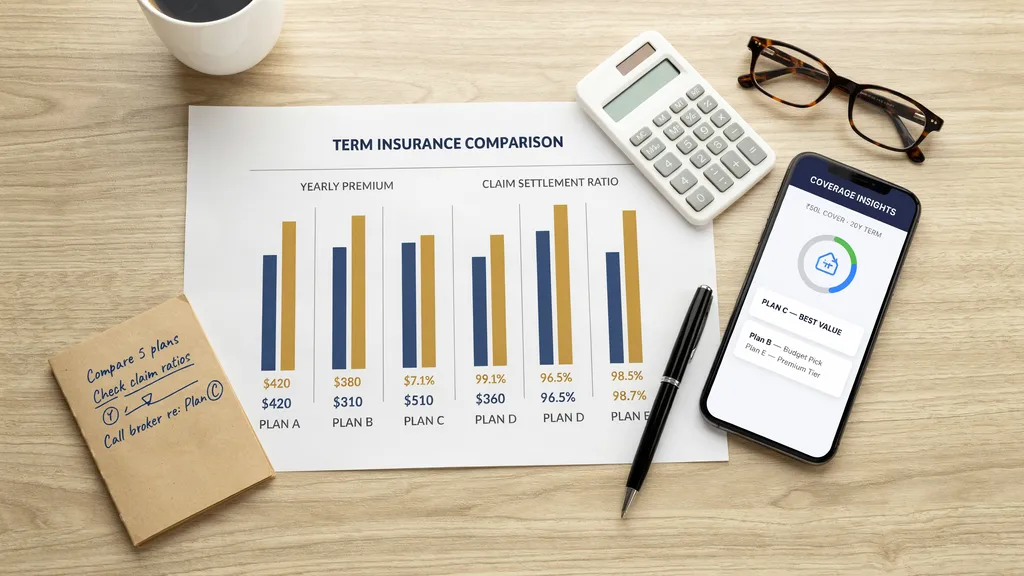
The table lists the five plans. It shows claim ratio and premium and a stand out feature. Two plans have a named premium. The other three sit in the same band. All five settle more than 98 percent of claims.
Best Term Insurance Plans in India 2026: Five Plans Compared (nyvo.in October 2026 update)
| Insurer and plan | Claim settlement ratio | Indicative yearly premium for ₹1 crore | Stand out feature |
|---|---|---|---|
| HDFC Life Click 2 Protect Supreme Plus | 99.6% | About ₹10440 | Premium waiver on critical illness or disability; cover to age 85 |
| Tata AIA Sampoorna Raksha Promise | 99.5% | ₹8856 to ₹10440 band | Joint life option; 50% terminal illness payout; cover to age 100 |
| Axis Max Life Smart Term Plan Plus | 99.3% | About ₹9528 | 150% cover on death in first 15 years; 64 illness rider |
| Bajaj Life eTouch II | 99.2% | ₹8856 to ₹10440 band | Premium pause up to 3 years; built-in disability waiver |
| ICICI Pru iProtect Smart Plus | 98.5% | ₹8856 to ₹10440 band | Cover top-up at life events; home loan boost |
HDFC Life leads on claim ratio at 99.6 percent. Axis Max Life has the lowest named premium at about ₹9528. Tata AIA covers a couple on one plan. Together they anchor the Best Term Insurance Plans in India 2026.
What Changes the Premium
Age is the biggest driver. Buying at 32 instead of 28 can cost about ₹2000 more a year. Smoking adds 40 to 60 percent. Women pay 20 to 30 percent less than men. Yearly payment saves 2 to 5 percent over monthly. Those rules apply to all Best Term Insurance Plans in India 2026.
Best Term Insurance Plans in India 2026: What Changes the Premium
| Buyer profile | Indicative yearly premium for ₹1 crore | Basis |
|---|---|---|
| Non-smoking man aged 30 cover to age 60 | ₹8856 to ₹10440 | nyvo.in May 2026 premium data |
| Non-smoking man aged 30 pure term | ₹12000 to ₹15000 | March 2026 advertorial estimate |
| Buying at 32 instead of 28 | About ₹2000 more a year | March 2026 advertorial estimate |
| Smoker | 40% to 60% higher than non-smoker | March 2026 advertorial estimate |
| Woman | 20% to 30% lower than a man | March 2026 advertorial estimate |
| Paying yearly instead of monthly | 2% to 5% saving | March 2026 advertorial estimate |
One advertorial from March 2026 quotes ₹12000 to ₹15000 for a 30 year old. The October comparison quotes ₹8856 to ₹10440. The gap comes from term length and insurer and discounts. Always compare on the same term in the Best Term Insurance Plans in India 2026.
How Much Cover You Need
₹1 crore is the usual floor and not a ceiling. Add your home loan balance and children’s education and ten years of household costs. A ₹40 lakh loan and ₹30 lakh for education already reach ₹70 lakh. Ten years of ₹50000 a month adds ₹60 lakh. Size the cover before you compare Best Term Insurance Plans in India 2026.
Best Term Insurance Plans in India 2026: How Much Cover You Need
| Need | Typical amount | Why it counts |
|---|---|---|
| Home loan balance | About ₹40 lakh | Family keeps the house |
| Children education | About ₹30 lakh | School and college fees |
| Household expenses for ten years | About ₹60 lakh at ₹50000 a month | Daily living without income |
| Total need | Above ₹1 crore | Why ₹1 crore is the usual floor |
| Rule of thumb | 10 to 15 times yearly income | Quick check before the detailed sum |
A quick rule is 10 to 15 times yearly income. Someone earning ₹10 lakh needs ₹1 crore to ₹1.5 crore. Subtract existing savings and cover. That sum guides your pick among the Best Term Insurance Plans in India 2026.
Claim Settlement Ratio Explained
The claim settlement ratio is the share of death claims paid in a year. IRDAI publishes it every year. A ratio above 95 percent is good. Below 90 percent is a warning sign. The October 2026 comparison uses a three year weighted average.
Look at the amount settled and not only the count. Some insurers pay many small claims and contest large ones. Check the complaint record too. Best Term Insurance Plans in India 2026 lists start here. The ratio is the first filter for the Best Term Insurance Plans in India 2026.
Riders Worth Paying For
Riders add cover for a small extra premium. A critical illness rider adds 20 to 30 percent to the base cost. A premium waiver on disability is built into some plans. Return of premium costs three to four times the pure term price.
Best Term Insurance Plans in India 2026: Riders Worth Paying For
| Rider or option | Typical cost | Verdict |
|---|---|---|
| Critical illness rider | Adds 20% to 30% to base premium | Useful if no separate health cover for illness |
| Accidental death benefit | Small add-on | Useful for frequent travellers |
| Premium waiver on disability | Built in on some plans | Keep it |
| Return of premium | Three to four times the pure term cost | Skip and invest the difference |
| Increasing cover | Varies by insurer | Useful to beat inflation if affordable |
Skip return of premium and invest the difference. Keep the disability waiver. Add critical illness only if you lack separate health cover. Riders shape the real value of the Best Term Insurance Plans in India 2026.
Top 5 Picks by Need
These five picks match a need to a plan. They use the claim ratio and premium and feature data above. Together they guide the choice among the Best Term Insurance Plans in India 2026.
Best Term Insurance Plans in India 2026: Top 5 Picks by Need
| Buyer need | Pick | Why |
|---|---|---|
| Highest claim record | HDFC Life Click 2 Protect Supreme Plus | 99.6% CSR and premium waiver |
| Cover for a couple | Tata AIA Sampoorna Raksha Promise | Joint life option and cover to 100 |
| Lowest named premium | Axis Max Life Smart Term Plan Plus | About ₹9528 with 150% early cover |
| Flexibility in tough years | Bajaj Life eTouch II | Premium pause up to 3 years |
| Home loan borrowers | ICICI Pru iProtect Smart Plus | Cover top-up at life events |
1. Highest Claim Record: HDFC Life Click 2 Protect Supreme Plus
The plan has a 99.6 percent claim settlement ratio. The premium is about ₹10440 for a 30 year old. It waives premiums on critical illness or disability. Cover runs to age 85 and terminal illness acceleration runs to age 80.
It costs a little more than the others. This is the safe pick in the Best Term Insurance Plans in India 2026.
2. Cover for a Couple: Tata AIA Sampoorna Raksha Promise
The plan has a 99.5 percent claim ratio. It offers a joint life option for a spouse. It pays 50 percent of cover on terminal illness. Cover can run to age 100. The critical illness rider covers up to 40 illnesses.
Couples with one income find this useful. This is the family pick in the Best Term Insurance Plans in India 2026.
3. Lowest Named Premium: Axis Max Life Smart Term Plan Plus
The plan has a 99.3 percent claim ratio. The premium is about ₹9528 for a 30 year old. It pays 150 percent of cover on death in the first 15 years. The critical illness rider covers up to 64 illnesses.
Early extra cover suits young borrowers. This is the value pick in the Best Term Insurance Plans in India 2026.
4. Flexibility in Tough Years: Bajaj Life eTouch II
The plan has a 99.2 percent claim ratio. It allows a premium pause of up to three years. Terminal illness pays up to ₹2 crore accelerated. A built-in waiver covers accidental total permanent disability.
The pause helps during job loss. This is the flexible pick in the Best Term Insurance Plans in India 2026.
5. Home Loan Borrowers: ICICI Pru iProtect Smart Plus
The plan has a 98.5 percent claim ratio. It allows a cover top-up at life events such as a home loan. The regular pay option can add 100 percent more cover on a home loan. A premium payback option exists at extra cost.
Borrowers who expect more loans like this. This is the borrower pick in the Best Term Insurance Plans in India 2026.
Tax Rules and GST
Term plan premiums qualify for deduction under the old tax regime. The deduction sat under Section 80C of the earlier Act. The Income-tax Act 2025 renumbered sections so check the current number. The death benefit is tax free under rules that were in Section 10(10D).
GST on individual life insurance premiums dropped to zero from 22 September 2025. The old rate was 18 percent. A ₹10000 premium that cost ₹11800 now costs ₹10000 before any base change. That cut lowers the cost of the Best Term Insurance Plans in India 2026.
For wider context see the World Economic Forum section on financial and monetary systems. The OECD insurance page offers comparative data on insurance markets. Both add background to the Best Term Insurance Plans in India 2026.
5 Costly Mistakes Buyers Make
Mistake 1: Buying Return of Premium
It costs three to four times the pure term price. Invest the gap instead. Pure term is the point of the Best Term Insurance Plans in India 2026.
Mistake 2: Choosing Too Short a Term
A 20 year term ends when children are still in college. Cover to age 60 or 65. Longer terms give better value per year. That holds across Best Term Insurance Plans in India 2026.
Mistake 3: Hiding Smoking or Health History
Undisclosed facts void claims. Declare everything. Accept a higher premium rather than risk rejection.
Mistake 4: Delaying the Purchase
Each year of delay raises the premium. A 28 year old pays about ₹2000 less a year than a 32 year old. Buy now.
Mistake 5: Ignoring the Claim Record
A cheap plan with a weak claim record is no bargain. Pick ratios above 95 percent. The record defines the Best Term Insurance Plans in India 2026.
Action Plan: Choosing the Best Term Insurance Plans in India 2026
Step 1: Fix the Cover Amount
Add loans and education and ten years of expenses. Subtract savings. Round up to the nearest ₹50 lakh.
Step 2: Fix the Term
Cover to age 60 or 65. Match the term to the year your youngest child turns 25.
Step 3: Shortlist by Claim Ratio
Keep insurers above 95 percent. Check the complaint record. Three or four plans remain.
Step 4: Get Two Quotes
Ask two insurers for the same cover and term. Compare after riders. Pay yearly for the discount.
Step 5: Declare and Buy
Declare smoking and health history. Complete medical tests. Keep the policy with your family. That completes your Best Term Insurance Plans in India 2026 plan.
Also read: Health Insurance Explained 2026: Premium Deductible and Coverage
Frequently Asked Questions
Q1: Which is the best term insurance plan in India for ₹1 crore?
One October 2026 comparison names five plans. HDFC Life Click 2 Protect Supreme Plus leads with a 99.6 percent claim ratio. Tata AIA Sampoorna Raksha Promise and Axis Max Life Smart Term Plan Plus follow. Bajaj Life eTouch II and ICICI Pru iProtect Smart Plus complete the list. All five settle more than 98 percent of claims. Premiums run about ₹8856 to ₹10440 for a 30 year old non-smoker. The Best Term Insurance Plans in India 2026 depend on your need. Pick HDFC Life for the claim record. Pick Tata AIA for a couple. Pick Axis Max Life for the lowest named premium. Compare two quotes before you buy.
Q2: How much does ₹1 crore term insurance cost for a 30 year old?
A non-smoking man aged 30 pays about ₹8856 to ₹10440 a year. That is for cover to age 60 per the October 2026 comparison. It used May 2026 data. A March 2026 industry article quotes ₹12000 to ₹15000 for pure term. The gap comes from term length and insurer and online discounts. Smokers pay 40 to 60 percent more. Women pay 20 to 30 percent less. Yearly payment saves 2 to 5 percent. The Best Term Insurance Plans in India 2026 cost less when bought young. Each year of delay adds to the premium. Get a quote for the same term from two insurers. Check the premium after GST became zero.
Q3: What is a good claim settlement ratio?
A ratio above 95 percent is good. Below 90 percent is a warning. The five Best Term Insurance Plans in India 2026 run from 98.5 to 99.6 percent. IRDAI publishes the ratio every year. The October 2026 comparison uses a three year weighted average. Look at the amount settled and not only the count of claims. Some insurers pay many small claims and contest large ones. Check the complaint record on the IRDAI site too. Ask how long claims take to settle. Keep nominee details updated. A strong ratio means little if your form hides facts. Declare everything at purchase.
Q4: How much term cover do I need?
Add your home loan balance and children’s education and ten years of household expenses. A ₹40 lakh loan and ₹30 lakh for education reach ₹70 lakh. Ten years of ₹50000 a month adds ₹60 lakh. The total passes ₹1 crore. A quick rule is 10 to 15 times yearly income. Someone earning ₹10 lakh needs ₹1 crore to ₹1.5 crore. Subtract existing savings and employer cover. The Best Term Insurance Plans in India 2026 should match that sum. Round up to the nearest ₹50 lakh. Review the cover after each loan or child. Some plans allow top-ups at life events. ICICI Pru offers that option.
Q5: Should I buy a return of premium plan?
Usually no. Return of premium costs three to four times the pure term price. A ₹10000 pure term plan can become ₹30000 to ₹40000. The returned money is only the premiums paid with no growth. Investing the ₹20000 to ₹30000 gap in an index fund usually beats it. The Best Term Insurance Plans in India 2026 are pure term plans. They pay only on death and cost the least. Keep insurance and investment separate. Use the saving for a mutual fund SIP. Buy pure term for the full need. Add only riders that cover real gaps. Skip the payback option.
Q6: What riders should I add?
Keep the premium waiver on disability because it is built in on some plans. Add a critical illness rider if you lack separate health cover for illness. It adds 20 to 30 percent to the base premium. Add accidental death benefit if you travel often. Consider increasing cover if inflation worries you. Skip return of premium. The Best Term Insurance Plans in India 2026 work best with two riders at most. Each rider raises the premium. Compare the rider cost with a separate policy. A standalone health plan often beats a critical illness rider. Read the rider wording for exclusions. Ask about the list of covered illnesses.
Q7: Is term insurance premium tax deductible?
Yes under the old tax regime. The deduction sat under Section 80C of the earlier Act. The ₹1.5 lakh limit is shared with other items. The Income-tax Act 2025 renumbered sections so check the current number with a tax adviser. The death benefit is tax free under rules that sat in Section 10(10D). The new tax regime does not allow the premium deduction. GST on individual life plans became zero from 22 September 2025. The Best Term Insurance Plans in India 2026 cost less after that change. Pay by bank transfer and keep receipts. Ask a tax adviser about your regime. Keep the policy document with the nominee.
Q8: What term length should I choose?
Cover to age 60 or 65 for most buyers. Match the end date to the year your youngest child turns 25. Longer terms cost more per year but give better value. A 30 year policy usually beats a 20 year one on cost per year. Some plans run to age 85 or even 100. Cover beyond retirement is rarely needed if savings are enough. The Best Term Insurance Plans in India 2026 let you pick the term at purchase. Changing it later is hard. Buy once for the full term. Review only if income or loans change sharply. Avoid very short terms that end during college years. Plan around the family’s timeline.
Q9: Do I need medical tests before buying?
Usually yes for ₹1 crore cover. Insurers ask for blood tests and ECG and sometimes more. Results decide acceptance and loading. Declare smoking and health history even if a test misses it. Hidden facts are the main reason claims fail. The Best Term Insurance Plans in India 2026 rest on honest disclosure. Accept a loading rather than risk rejection. Keep copies of test reports. Some insurers waive tests for young healthy buyers below a certain sum. Ask what tests are needed before you apply. Schedule tests early because approval takes days. Review the proposal form before you sign. Tests protect your family’s claim.
Q10: Can I buy term insurance online?
Yes and it is often cheaper. Online purchase can bring 10 to 15 percent discounts per one March 2026 article. The process takes a few days including medical tests. Compare the same cover and term on each insurer’s site. Check the claim ratio and the complaint record first. The Best Term Insurance Plans in India 2026 are all sold online. Read the policy wording before payment. Add nominee details carefully. Keep the policy PDF with your family. Set a yearly reminder for the premium date. Pay yearly for the 2 to 5 percent saving. Call the insurer helpline if any question remains. Buy from the insurer’s own site or a licensed broker.
Conclusion
The Best Term Insurance Plans in India 2026 share three traits. They settle more than 98 percent of claims. They cost about ₹8856 to ₹10440 a year for ₹1 crore at age 30. They offer useful riders without forcing return of premium. HDFC Life and Tata AIA and Axis Max Life lead the list.
Fix the cover amount first. Cover to age 60 or 65. Shortlist by claim ratio. Get two quotes and declare everything. That is how to choose the Best Term Insurance Plans in India 2026.
This guide on the Best Term Insurance Plans in India 2026 is general information. It is not insurance or financial or tax advice. Premiums and ratios change. Confirm all details in the policy wording and with the insurer before you buy.
1 thought on “Best Term Insurance Plans in India 2026: Premium for 1 Crore Cover”